Minnesota’s severe weather season can be brutal. One minute you’re enjoying a summer evening, and the next, golf ball-sized hail is pummeling your roof and siding. If you’ve recently experienced hail damage, you’re probably feeling overwhelmed and unsure where to start.
Here’s the thing: what you do in the next 72 hours could make or break your insurance claim. Every year, thousands of Minnesota homeowners make preventable mistakes that cost them thousands of dollars in denied claims or reduced payouts.
Let’s walk through the seven most common mistakes homeowners make after hail damage – and more importantly, how to avoid them.
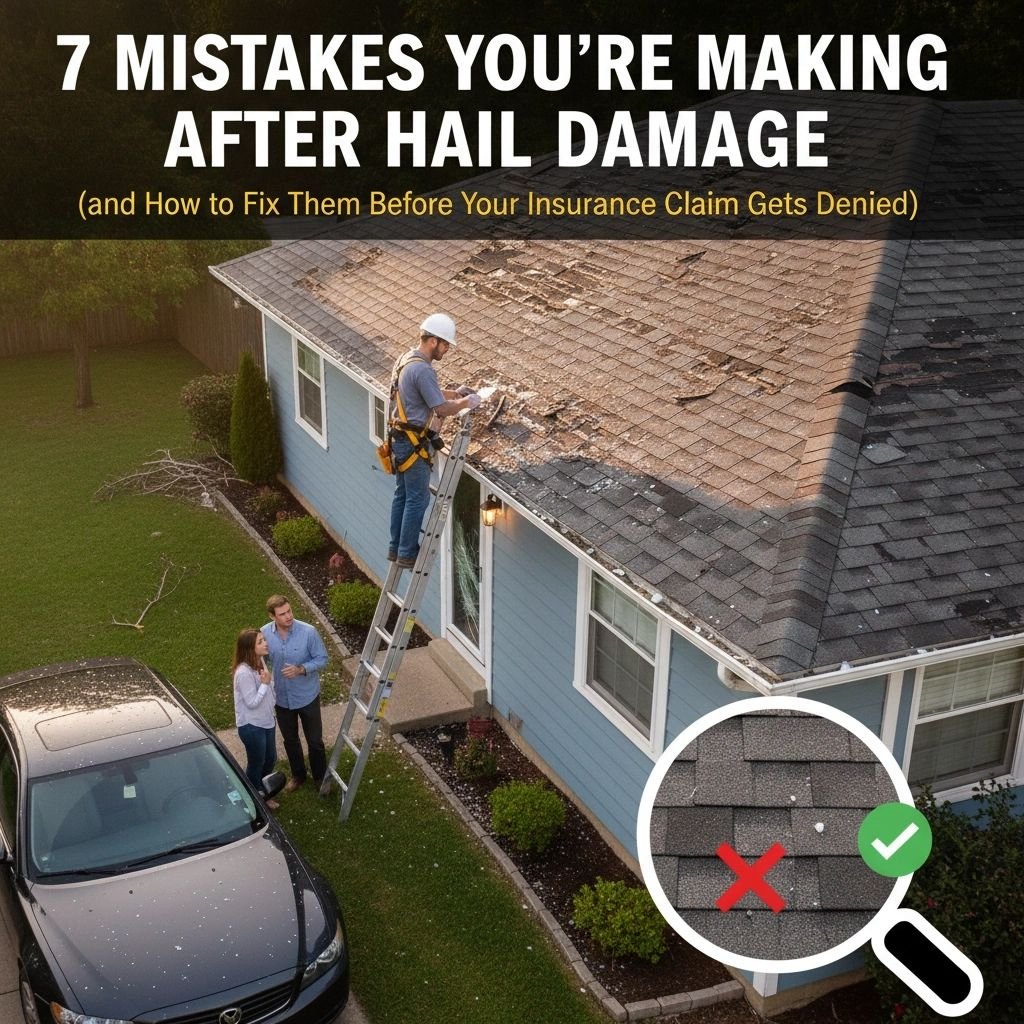
Mistake #1: Taking Poor Photos (or None at All)
This is the big one. After a storm hits, many homeowners either forget to document the damage or take blurry, poorly lit photos that don’t show the real extent of what happened. Your insurance company needs clear evidence that the storm – not normal wear and tear – caused the damage.
How to Fix It: Grab your phone and start documenting everything immediately. Take photos from multiple angles, including close-ups and wide shots. Don’t just focus on obvious damage – photograph your gutters, downspouts, window screens, outdoor furniture, and even your landscaping.
Make sure your photos are well-lit (natural daylight works best) and show clear detail. If you have a ladder and feel safe using it, get some shots from higher up, but don’t risk injury. Most importantly, take «before» photos of undamaged areas for comparison if possible.
Pro tip: Time-stamp your photos and include reference points like house numbers or distinctive features so it’s clear these photos are of your property.
Mistake #2: Waiting Too Long to Call Your Insurance Company
Minnesota homeowners often think they need to have everything figured out before calling their insurance company. Wrong. Every day you wait makes it harder to prove the damage came from the recent storm rather than gradual deterioration.
How to Fix It: Call your insurance company within 24-48 hours of the storm, even if you haven’t finished assessing all the damage. Most insurance policies require «prompt» notification, and while that’s not specifically defined, sooner is always better.
When you call, you’ll get a claim number and start the paper trail. You can always add more damage to your claim as you discover it, but you can’t go back in time to report it promptly.
Mistake #3: Starting Repairs Before the Adjuster Sees Everything
This mistake is heartbreaking to watch. A homeowner gets a tarp on their roof (good!) but then decides to «fix a few shingles» before the adjuster arrives (bad!). Once you alter the damage, the adjuster can’t see what the storm actually did to your property.
How to Fix It: Document first, protect second, repair last. After you’ve thoroughly photographed everything, make temporary repairs to prevent further damage – but don’t make permanent fixes until after your adjuster has seen and documented the original damage.
Temporary repairs might include tarping a roof, boarding up broken windows, or covering damaged siding. Keep all receipts for materials used in temporary repairs – these costs are often covered by your insurance.
Mistake #4: Trying to Handle Everything Yourself
Minnesota weather is unique, and so is the damage it causes. Hail damage isn’t always obvious – especially on roofs. What looks like a few missing shingles from the ground might actually be extensive damage that requires a complete roof replacement.
How to Fix It: Get a professional inspection from a local contractor who knows Minnesota weather patterns. A contractor like Minnesota Custom Exteriors has seen how our specific climate and storm patterns affect different roofing and siding materials. They know what to look for and can spot damage you might miss.
Local contractors also understand how insurance companies in our area typically handle claims. This knowledge can be invaluable during the process.
Mistake #5: Falling for Storm Chasers
After every major storm, out-of-state contractors flood affected areas. These «storm chasers» often promise quick fixes and guaranteed insurance approval. Some are legitimate, but many are not. Even the legitimate ones often lack proper licensing for Minnesota work and don’t understand our local building codes.
How to Fix It: Choose a local contractor with a proven track record in Minnesota. Local contractors will be here long after the storm chasers have moved on to the next damaged area. They’re also familiar with Minnesota building codes, permit requirements, and local supplier relationships.
Before hiring anyone, verify their Minnesota contractor’s license, check their Better Business Bureau rating, and ask for recent local references. A reputable local contractor will be happy to provide this information.
Mistake #6: Not Being Present During the Insurance Inspection
When your insurance adjuster comes out, don’t just hand them your keys and let them work alone. Many adjusters are thorough and fair, but they’re also human – they can miss things, especially if you’re not there to point out specific areas of concern.
How to Fix It: Be present during the entire inspection. Walk around with the adjuster and point out all the damage you’ve documented. Bring your photos and ask questions about anything that seems unclear.
Consider having your contractor present during the inspection too. An experienced local contractor can help identify damage the adjuster might overlook and explain technical aspects of the damage in terms the adjuster will understand and document properly.
Mistake #7: Accepting the First Settlement Offer Without Review
Insurance companies often send an initial settlement check quickly after the inspection. Many homeowners assume this represents the full value of their claim and cash it immediately. However, initial settlements are often conservative estimates that may not cover the full scope of necessary repairs.
How to Fix It: Before accepting any settlement, have a qualified local contractor review the adjuster’s estimate. Make sure it includes all necessary repairs, proper materials, and current labor costs for the Minnesota market.
If the settlement seems low, you can negotiate with your insurance company. Provide additional documentation, get independent estimates, and don’t be afraid to ask questions. Remember, you’re paying for insurance coverage – you have every right to receive fair compensation for covered damage.
Working with the Right Local Partner
Dealing with hail damage and insurance claims can be overwhelming, but you don’t have to navigate this process alone. Working with an experienced local contractor who understands Minnesota’s unique weather challenges and insurance landscape can make all the difference.
At Minnesota Custom Exteriors, we’ve helped countless Minnesota homeowners through this process. We know what local insurance adjusters look for, understand Minnesota building codes, and have relationships with suppliers who can get your materials quickly – even during busy storm seasons.
The key to avoiding these costly mistakes is acting quickly, documenting thoroughly, and working with professionals who know Minnesota weather and insurance processes inside and out. Don’t let preventable errors turn a manageable insurance claim into a financial disaster.
Remember, your insurance policy is there to protect you – make sure you’re taking the right steps to get the full benefit of that protection. When Minnesota weather throws its worst at your home, being prepared and working with the right local team can help you weather the storm and come out stronger on the other side.